America’s federal tax base currently generates over $5 trillion annual. The nation has an attended annual budget expenditure that exceeds $7 trillion. In order to meet the expenditure, the federal government borrows over $2 trillion annually. In the period from the founding of the republic in 1776 up to the year 2017 (241 years), the accumulated national debt reached $20 trillion. In just nine years, from 2017 to 2026, the national debt has doubled to $40 trillion. In other words, the accumulation of national debt in the United States is accelerating, rapidly. In the words of one financial analyst, “there is no stopping this train.”
Read more Is America’s Healthcare Crisis a Sleeper Issue for the Midterms?
The question that now begs an answer is straightforward: how long can this U.S. deficit spending binge go on without a debt crisis?
A national debt of $40 trillion represents about 123 percent of the projected U.S. GDP. Around the globe many countries have similar debt-to-GDP profiles. IMF projections for 2026 show the United Kingdom at 102 percent, France 118 percent, Italy 118 percent, Canada 115 percent, China 104 percent, Brazil 97 percent, and the worst profile of all being Japan at over 200 percent. There is a common problem driving all these debt profiles: aging populations and unfunded government liabilities and interest paid on national debt.
Unfunded U.S. government liabilities are estimated to exceed $100 trillion over the coming years, with some estimates running as high as $150 trillion (no one knows for sure.) In addition, interest alone on the $40 trillion national debt will exceed $1 trillion this year. As low-cost debt is refinanced into high-cost debt, interest expense will soon become the largest line-item expenditure in the entire federal budget. These same forces are driving debt accumulation in most developed nations around the globe.
The Inevitable
We’re facing two very different timelines for this crisis: an inevitable debt crisis and an imminent debt crisis. Neither is a good scenario.
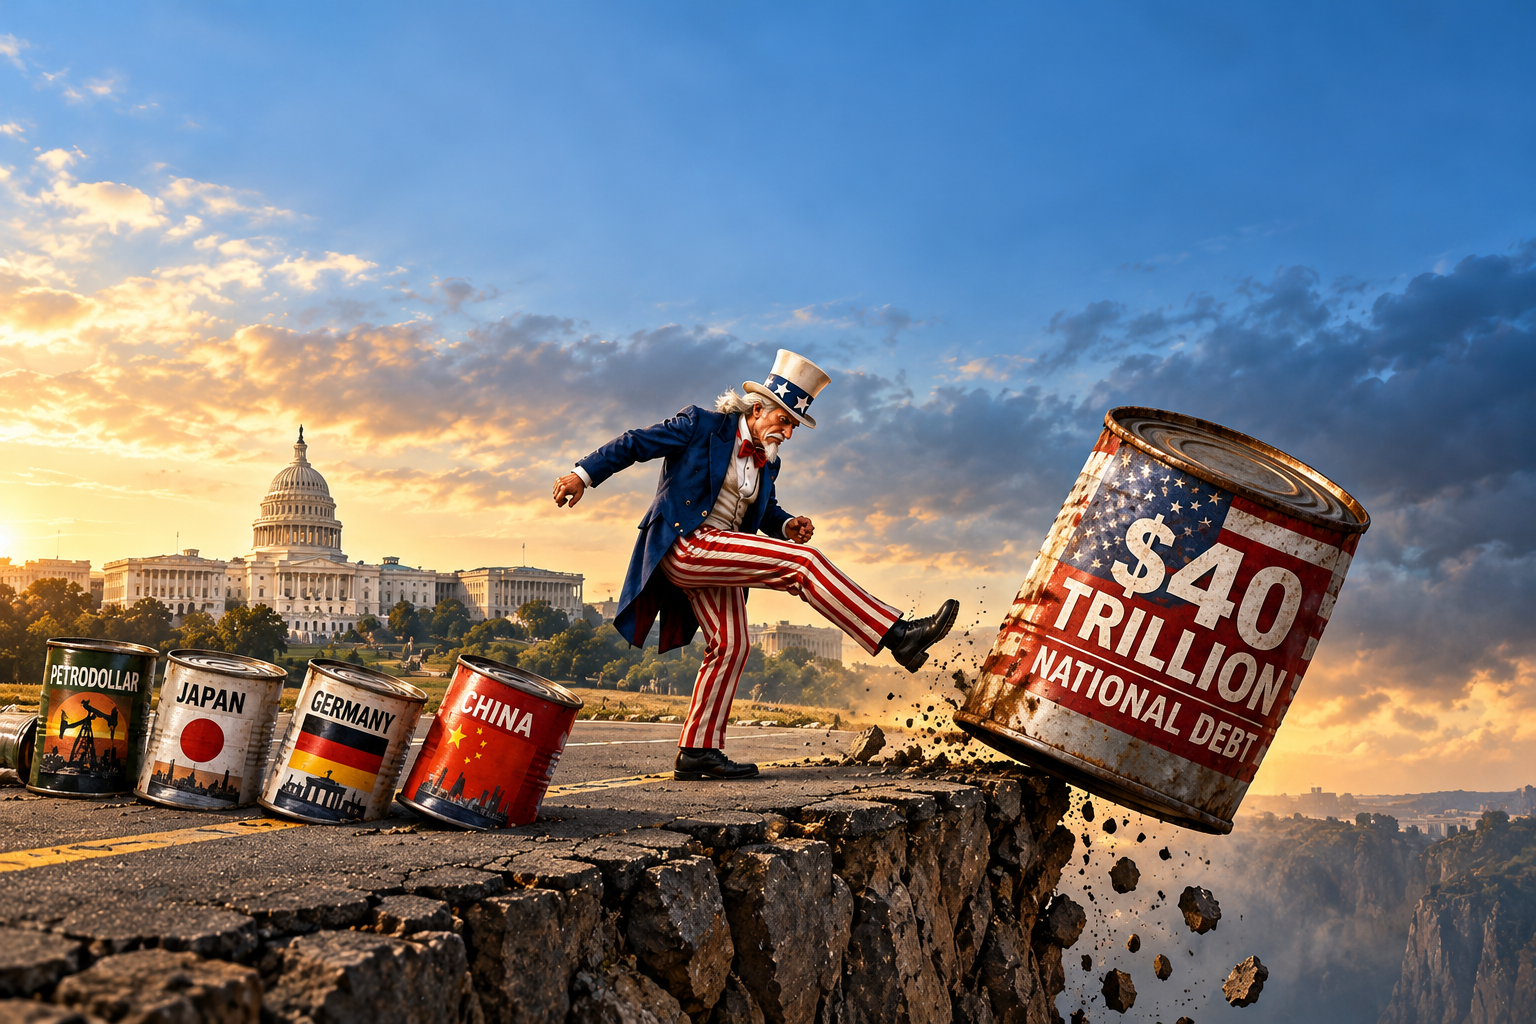
I for one have been caught in the trap of thinking the imminent was always just around the corner. An inevitable debt crisis has been very visible for 30 years. The imminent part has always had a can to kick. Here are the four significant cans that have been kicked over the past 50 years.
Can Kicking
The first can kicked to avoid a U.S. debt funding crisis occurred in the early 1970s with the U.S.-facilitated creation of the petrodollar. Surplus USD (United States Dollar) generated by OPEC oil exporting nations were recycled into the U.S. Treasury bond market.
The second can kicked was in the early 1980s when the Reagan administration increased defense spending to bankrupt the Soviet Union and U.S. deficits increased in lock step. That spending coupled with record high interest rates under the Volcker Federal Reserve sent the USD up and the Yen dramatically down. Japan’s exporters entered the U.S. consumer markets on the back of a weak Yen. Japan purchased over $1 trillion of U.S. Treasury debt.
The third can kicked came with the fall of the Berlin Wall coupled with the collapse of the Soviet Union and the U.S.-facilitated reunification of West and East Germany. A reunified Germany did what Germans always do: they created a manufacturing juggernaut in the heart of Europe that generated trade surpluses.
Read more Why Trump Is Backing Netanyahu in Israel’s Crucial Election
The fourth and last can kicked was the U.S.-facilitated entry of China into the World Trade Organization in 2002. In ten short years, a significant portion of America’s manufacturing base was transferred to China in order to profit from cheap labor there. China’s peak export foreign exchange holdings (in all currencies) hit $3.8 trillion in 2013 and its ownership of U.S. Treasury securities was $1.3 trillion of that peak.
All four kicked cans have backstories that space does not allow for further discussion here. Suffice it to say, that directly or indirectly, offshore capital flowed into the U.S. Treasury bond market for 50 years to enable the financing of never-ending deficit spending. The visibility of an inevitable debt crisis became crystal clear over 30 years ago. For the past 50 years, a primary focus of the U.S. Treasury always was and always has been securing offshore funding for Washington’s deficit spending. Even if it cost 20 million American blue-collar manufacturing jobs and facilitated the eruption of a fentanyl/opioid addiction epidemic among a whole generation of middle-class workers who couldn’t be “re trained” into meaningful new occupations.
The Imminent
The question that now begs an answer is straightforward: how long can this U.S. deficit spending binge go on without a debt crisis? The math related to the current levels of debt — plus the interest expense required to support it — is on track to force something to eventually break in the United States and/or global financial markets. Will there be an attempt on the part of government(s) to avert a crisis before something breaks?
Historically, going back to before the Roman empire, there have been four prominent aversion tactics for governments: 1) war will destroy debt, 2) austerity, if it can be tolerated, can eliminate debt, 3) accelerated economic growth can shrink debt, and 4) deliberate inflationary government policies will compress debt. Of the four — war, austerity, economic growth, inflation — it is inflation that tops the list.
Inflation is the non-legislated tax on every American taxpayer that for some reason many don’t seem to connect directly to government policies. Gradual inflation takes time to compress a mountain of debt. And time is not on anyone’s side.
There is an increasing high probability that something will break in the financial markets. The sudden cause could be a failed Treasury bond auction. It could also be the bursting of the stock market’s AI bubble. It could be a European civil war that could erupt in France or England or both. It could be China deciding to invade Taiwan. It could be a U.S. attack on Iran that fails to topple the IRGC. It could be a Russian attack on a NATO member state that’s supplying Ukraine with the critical components to manufacture drones. It could be none of the above, but instead some event that isn’t even remotely on anyone’s radar screen.
Much of that remains unclear. But this seems more certain: Sometime in the next two months to two years, there is a very high probability that an event will cause something to break. And that’s pretty imminent relative to a 50-year timespan. Buckle up.
Read more NFL Games Are Getting Longer. Will More Instant Replay Make Things Worse?
READ MORE from Fred A. Kingery:
Is a Great American Bankruptcy Coming?
Are We Going the Way of Argentina?
The U.S. Treasury’s Coming Financial Apocalypse
About the Author